What's Actually Driving Your Car Insurance Increase This Year
Your renewal letter blames rising costs, and gas is up to $4.10 a gallon this August, so the story checks out. It just isn't the real one. Repair costs climbed 36 percent since 2021, total losses hit a record 23.1 percent of claims, and the number that actually moves your premium has almost nothing to do with what you pay at the pump.
The Line on the Renewal Notice
Your car insurance renewal arrived with a number that's higher than last year's, and somewhere in the letter or the phone call that followed, someone mentioned rising costs. Maybe they said it in those exact words. Given what's happened at the pump this year, it's an easy story to believe. The national average for a gallon of regular gasoline hit $4.10 in the third week of August, the highest it's ever been for that date, and the monthly average for August is running at $4.06, above the $3.97 record set back in 2022. If gas costs more, it feels reasonable that everything tied to driving costs more too.
Nationally, though, the premium picture is far less dramatic than that story suggests. Auto insurance rates are projected to rise by roughly 1 percent on average across the country in 2026, according to the rate-tracking firm Insurify, a sharp slowdown after rates fell about 6 percent in 2025 and rose a modest 3 percent the year before that. Some of you are seeing far bigger jumps. New Jersey drivers are facing filed increases around 10.46 percent, Nevada around 6.42 percent, and more than half of states could actually see rates go down. The number on your own letter has almost nothing to do with the national average and almost everything to do with your state, your carrier, and your own claims history. Gas prices are a real and visible cost for you as a driver. Whether they're the reason your specific bill went up is a separate question, and the honest answer is: probably not much of one.
What "Loss Cost Trend" Actually Means
Nobody at an insurance company files a rate increase with a state regulator and writes "gas is expensive" as the justification. What actually shows up in those filings is a phrase called the loss cost trend: the rate at which claims payouts are rising relative to the premiums the insurer is collecting. For four straight years now, loss costs have outpaced premiums in the personal auto line, which is the underlying reason state regulators have approved wave after wave of rate filings since 2024. Many of those approved increases are only now landing on renewals as policies come up throughout 2026, which is part of why a hike you're seeing this fall can feel disconnected from anything that happened to you personally this year.
Loss cost trend is a boring phrase, and boring phrases don't make for compelling customer service scripts. "Rising costs" is vaguer and easier to say out loud, and it isn't technically false, it's just doing a lot of work to avoid naming which costs. The honest list is repair bills, parts, labor, and the growing number of crashes that total a car outright. Fuel is on that list too, but it's a small piece, not the headline.
The Repair Bill Behind the Number
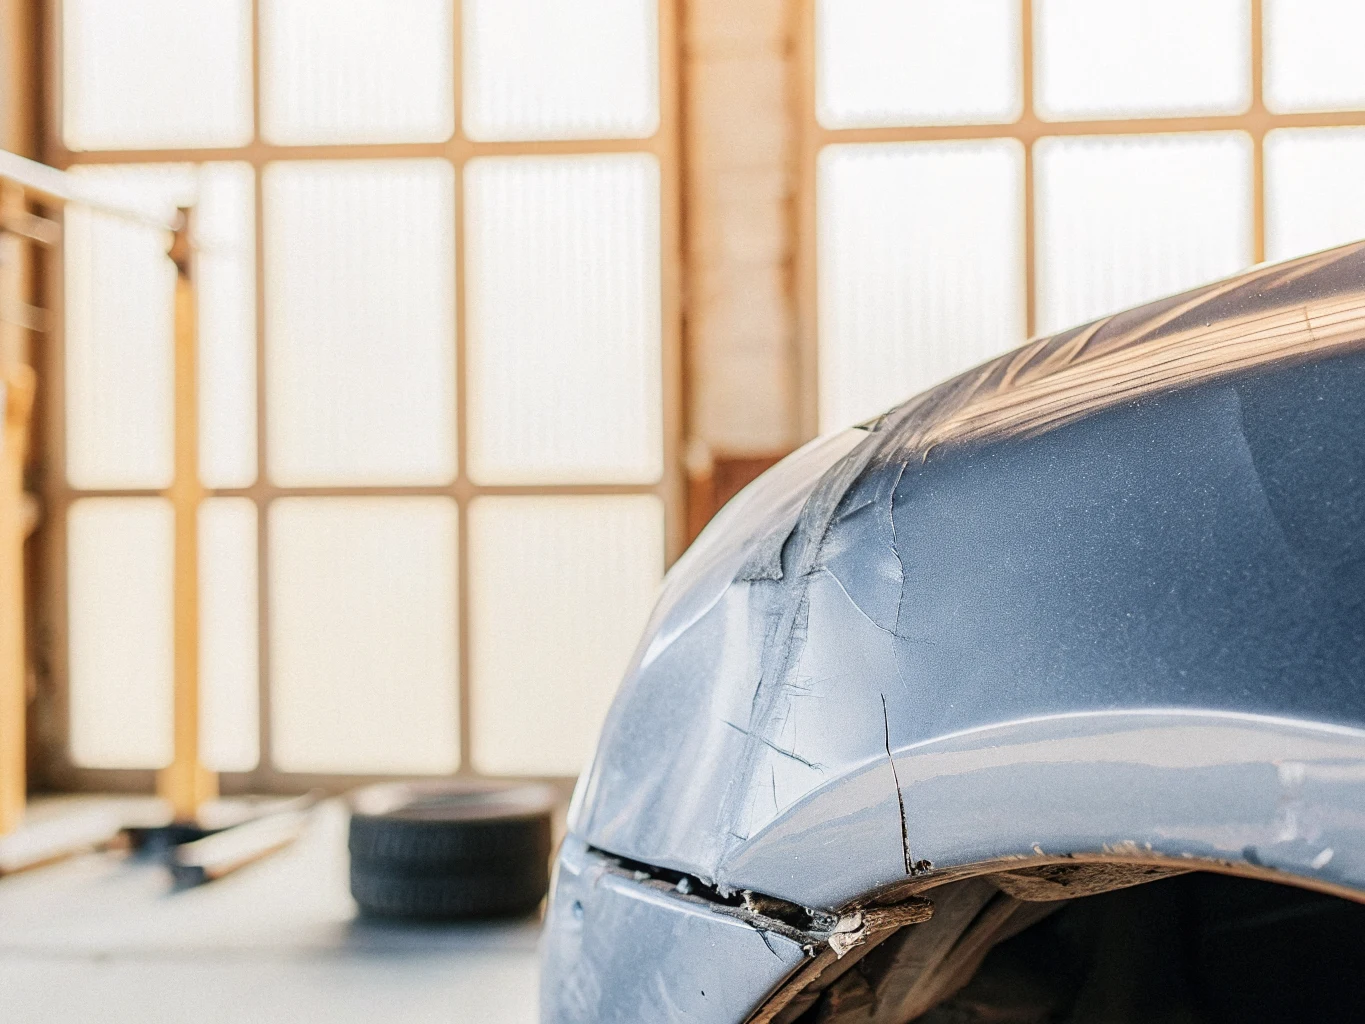
Here's the part of the story that actually shows up in loss cost filings. The cost of vehicle repairs and maintenance climbed more than 36 percent between 2021 and 2025, with bodywork and repair labor each rising over 13 percent on their own. The average repair now runs $4,818, up from a fraction of that five years ago. Replacement parts costs have climbed a cumulative 45 percent over the same four-year stretch, driven by supply chain disruption and a nationwide shortage of trained auto body technicians that has pushed labor rates up faster than general wage growth.
Newer cars make this worse, not better. Advanced driver-assistance sensors, the cameras and radar units behind lane-keeping and automatic braking, now require calibration on 28.3 percent of repairable estimates, adding $350 to $500 per system on top of the bodywork itself. A fender-bender that would have been a simple panel swap a decade ago now often means a sensor recalibration bill stacked on top.
Then there's the tariff layer. About 6 in 10 replacement auto parts used in U.S. repair shops are imported from Mexico, Canada, and China, and a 25 percent tariff on those parts is now in effect. Insurify's own modeling suggests tariffs alone could push the national average premium increase from around 1 percent up toward 4 percent by the end of 2026, entirely separate from anything related to fuel or the broader inflation story. That's a mechanical, traceable cost: a part costs more to import, the insurer pays more to replace it, the loss cost trend moves, and your premium eventually follows.
More Claims End in a Totaled Car Now
There's a second piece that has nothing to do with how many accidents happen and everything to do with how expensive each one is once it does. A record 23.1 percent of all auto claims resulted in a total loss in 2025, according to the claims analytics firm CCC Intelligent Solutions, the highest share on record. That's not more crashes. It's more crashes where the repair bill now exceeds what the car is worth, which happens faster when repair costs are climbing the way they have been.
Severity is rising on the injury side too. Average paid bodily injury claim severity is up 10.3 percent year over year and roughly 32 percent over the past four years, and the average bodily injury liability claim now runs well into five figures, several times the average property damage payout on the same policy. None of that shows up as a story you'd notice day to day. It shows up eighteen months later as a loss cost trend line that your insurer's actuaries are required to account for when they file for a rate change.
Where the Oil Shock Actually Fits In
It would be dishonest to leave oil out of this entirely, because something genuinely unusual has happened to it this year. Disruption tied to the conflict in the Middle East and reduced tanker traffic through the Strait of Hormuz, the waterway that handles roughly a fifth of the world's oil flow, sent Brent crude up by around 65 percent in the first months of 2026. The U.S. Energy Information Administration revised its full-year Brent forecast from $58 a barrel to $79 a barrel inside a single month. That's the mechanism behind the $4.10 gas price on your receipt, and it's real, and it's expensive for you specifically as a driver filling a tank.
What it is not, at least not directly, is a major input into what your insurer pays out on claims. An insurance company's loss costs are repair bills, parts, labor, medical payments, and legal costs, not the price of the gasoline in your tank. The oil shock touches your insurer's world more indirectly, through the general inflation it has fed into the broader economy. The 10-year Treasury yield climbed from about 4.19 percent in January to roughly 4.66 percent by August, with a stretch above 4.7 percent, as investors priced in stickier inflation expectations tied partly to energy costs. The University of Michigan's preliminary consumer sentiment reading fell to 51 in August, down 7.6 percent from July, with year-ahead inflation expectations rising to 4.3 percent. People are feeling this squeeze, and they're right to.
Here's the nuance worth sitting with, though. Higher bond yields aren't purely bad news for an insurance company. Insurers hold large fixed-income portfolios and earn investment income on the premiums they collect before claims come due, so a higher 10-year yield actually improves that side of their balance sheet, offsetting some of the pressure from rising claims costs rather than adding to it. Inflation is not a one-directional force pushing your premium up. It pushes on parts and labor costs, which does raise your premium, while simultaneously helping insurer investment returns, which works the other way. A rate filing that leans entirely on "the economy" without naming a specific loss cost is skipping past that offset.
So is "gas prices" a real reason for your renewal number, or a convenient one? Both, in different proportions than most renewal conversations let on. The general inflationary environment tied to the oil shock is real and it is touching the parts and labor side of repair costs, alongside the tariffs, alongside the technician shortage, alongside the sensor calibration requirements on newer cars. All of that is genuinely showing up in loss cost trends. But when a customer service rep or a renewal letter reaches for "gas is expensive" as shorthand for all of that, they're reaching for the one input that you, the driver, feel most directly and viscerally, not the one that's actually moving the number on your bill the most.
The parts tariff alone is doing more to your premium than fuel prices are. The record total-loss rate is doing more. The technician shortage pushing labor rates up is doing more. Fuel is a real cost, it's just mostly your cost, at the pump, not your insurer's cost, in a repair estimate. Conflating the two makes for a tidier conversation, but it's not the mechanism actually driving what you're being asked to pay.
What Shopping Your Renewal Actually Gets You
This is where the state-by-state and carrier-by-carrier variation actually matters to you. Among major insurers, Allstate filed the largest average rate hike this year at 1.98 percent, while State Farm customers are seeing average decreases of around 4 percent at renewal. Two neighbors with identical driving records and nearly identical cars can be moving in opposite directions purely based on which company they're with, which means your renewal number says almost nothing about whether you're getting a fair deal until you check it against the market.
The data on shopping around backs this up more strongly than most personal finance advice does. Getting quotes from at least three companies saves drivers an average of $709 a year, according to the comparison site MoneyGeek, and some drivers uncover gaps of more than $8,500 annually between what they're paying and what a comparable policy costs elsewhere. A separate NerdWallet analysis from this August found that drivers who never compare rates can end up overpaying by as much as $2,414 a year. Insurers count on renewal inertia. The rate increase on your letter is not a fixed number you have to accept, it's an opening offer from a company betting you won't ask anyone else for a quote.
Telematics, Deductibles, and the Trade-Offs That Are Actually Yours to Make
If you'd rather not shop every renewal, the two levers you actually control are usage-based discounts and your deductible, and both have real numbers attached to them rather than marketing language.
Telematics programs, the ones that track your driving through an app or a plug-in device, save safe drivers an average of 10 to 30 percent depending on the company and how you actually drive. Allstate and Nationwide advertise caps as high as 40 percent for their best drivers, Progressive's Snapshot program averages a $231 discount, and most carriers hand you 5 to 10 percent just for enrolling before your driving data comes into play at all. The catch is real: these programs score you on your actual habits, including hard braking, late-night driving, and phone handling, and roughly 1 in 5 enrollees in some programs end up paying more, not less, once the data comes in. If you commute mostly on highways during daylight and you're not a phone-in-hand driver, this is close to free money. If your daily drive is stop-and-go city traffic at odd hours, run the math before you opt in.
Your deductible is the more predictable trade. Raising your collision and comprehensive deductible from $500 to $1,000 cuts the premium on that coverage by an average of about 9 percent, saving the typical driver around $269 a year, though the exact number swings by state; Massachusetts drivers have seen savings closer to 19 percent, Michigan drivers closer to 4 percent. The math only works if you actually have $1,000 sitting somewhere you can reach it without a scramble. A lower premium that assumes a cushion you don't have isn't a discount, it's a bet against your own emergency fund.
| What's moving | Approximate scale | Whose cost is it |
|---|---|---|
| Auto parts tariffs (25% on imported parts) | Could add up to 3 pts to the national premium trend by year-end | Insurer's loss cost |
| Repair cost inflation, 2021-2025 | Up 36% cumulative; avg. repair now $4,818 | Insurer's loss cost |
| Record total-loss rate | 23.1% of claims in 2025 | Insurer's loss cost |
| Gasoline (national average, Aug. 2026) | $4.10/gallon, a record for the date | Your fuel budget, not your premium |
| Shopping 3+ quotes at renewal | Averages $709/year saved | Your leverage, not the insurer's cost |
Ask Your Agent Which Number Actually Moved
The next time a renewal letter cites rising costs, ask a more specific question than the letter invites: which loss cost went up, parts, labor, claims frequency, or claims severity, and by how much. A carrier that can't answer that, or that just repeats "the market" back at you, is telling you it filed the increase because everyone else did, not because your driving record or your car's repair profile changed. A carrier that can point to a specific number, a rising total-loss rate in your state, a parts tariff hitting a model you drive, gives you something to actually compare against a competing quote. Gas prices make for a sympathetic headline. The parts bin and the body shop are where your premium is actually being written.