The FSA Balance You Forfeit on December 31
You put $3,000 into your health FSA in January, pre-tax, and it felt like free money. If there's $700 left in it at midnight on December 31 and your plan has no carryover, that money doesn't roll over, doesn't refund, and doesn't come back. It goes to your employer. Here is how to spend it down before it evaporates.
The Money You Already Earned and Might Still Lose
A health flexible spending account is one of the better deals in your benefits packet. You decide in the fall how much to set aside for next year, up to $3,400 for 2026, and that money comes out of your paycheck before taxes, which means a $3,400 election costs you noticeably less than $3,400 in take-home pay. Free money, more or less. Then December arrives, and the same account that saved you on taxes turns into a countdown, because if you don't spend it, you don't keep it.
This is the part that stings. Say you've got $700 sitting in the account on December 31. It doesn't roll into your savings. It doesn't get refunded on your W-2. If your plan has no carryover and no grace period, at midnight that $700 reverts to your employer. You earned it. You set it aside. And you can still hand it back by doing nothing, which is the single most common FSA mistake there is.
Use-It-or-Lose-It Has Exactly Two Exceptions
The default rule is blunt: unspent FSA money at the end of the plan year is forfeited. The IRS allows employers to soften that with one of two options, and the word "one" is doing real work, because a plan can offer either but never both.
The first is a carryover. Your plan may let you roll up to $680 of unused funds into the next plan year for 2026, and that's it, $680, not the whole balance. Anything above that is still forfeited. The second is a grace period: instead of a carryover, the plan gives you an extra two months and fifteen days into the new year to incur expenses against the old balance. Some plans offer one, some the other, and some offer neither and enforce a hard December 31 wall. The only way to know which one you have is to check your specific plan documents, and this is the week to do it, not the week after.
Why the FSA Punishes You and the HSA Doesn't
People mix up the FSA and the HSA constantly, and the difference is exactly the part that matters right now. A health savings account, the HSA, is yours. You own it, the balance rolls over year after year with no deadline, and it follows you when you change jobs. Nothing about December 31 threatens an HSA. That's why it's the better long-term account, and it's a different animal.
The FSA is structured the opposite way on purpose. Because your employer fronts your full annual election on day one, before you've contributed most of it, the use-it-or-lose-it rule is the tradeoff that makes that arrangement work for them. The forfeited balances that revert to employers are, in effect, the pool that offsets the risk of employees who spend their full election early and then leave. Knowing that doesn't change the rule. It just tells you the deadline is a feature of the account, not an accident, and the account is counting on you to forget.
What Actually Counts, and What Doesn't
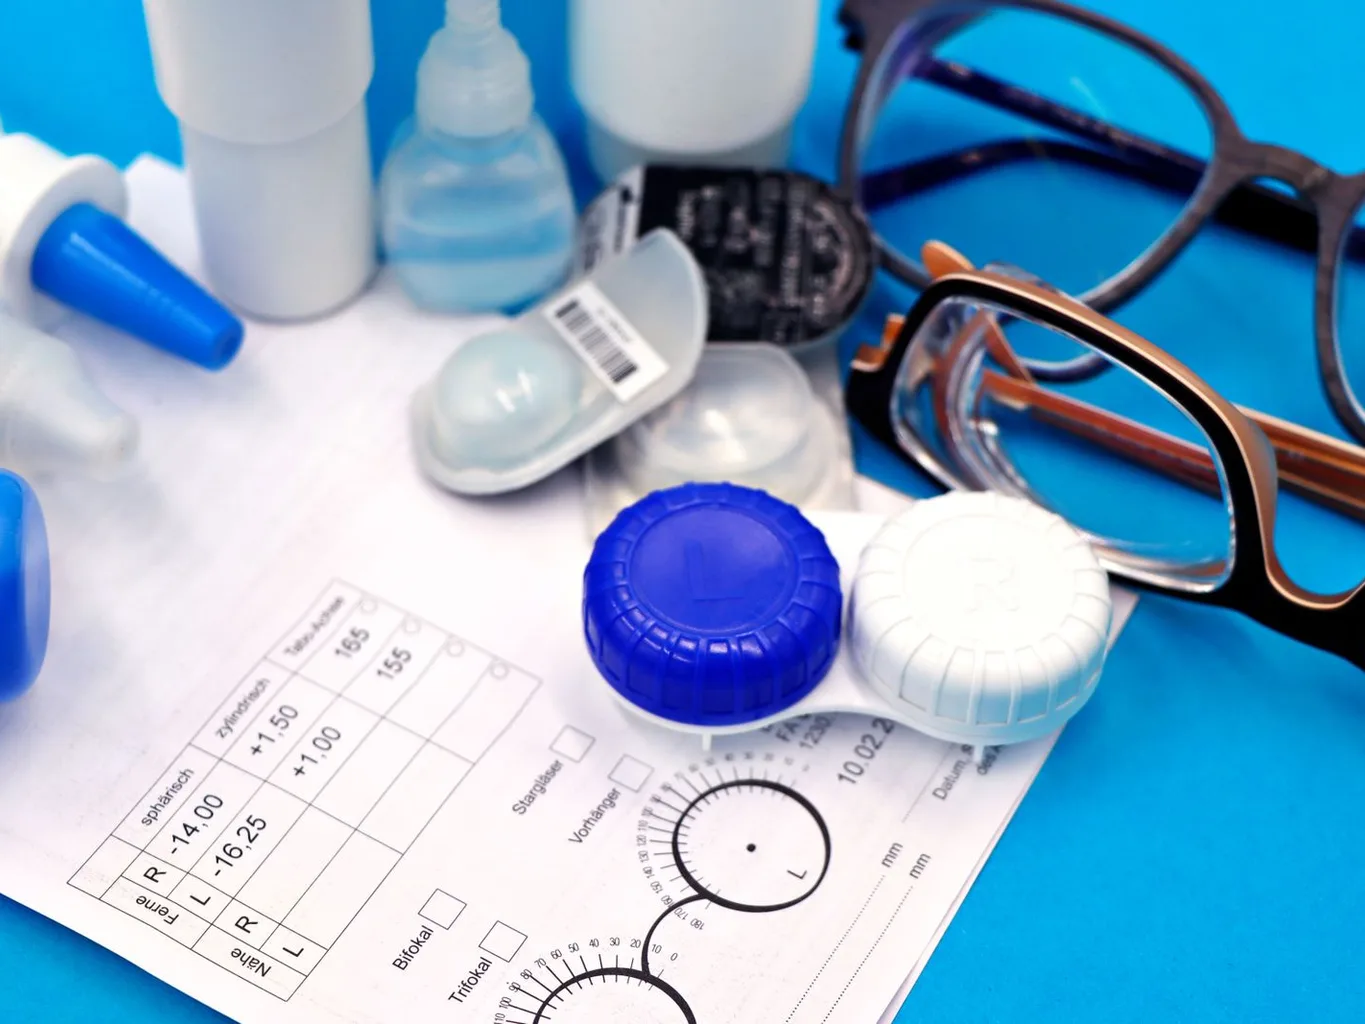
The good news is that eligible expenses are broader than most people spend them on. Prescription copays and deductibles are obvious. So are new glasses and prescription sunglasses, a year's supply of contact lenses, and dental work you've been postponing. Over-the-counter medications qualify without a prescription now, and so do menstrual products, sunscreen above a certain SPF, first-aid supplies, and a long list of items you'd otherwise buy with taxed dollars anyway.
What doesn't count is the trap people fall into when they panic-spend in late December: cosmetics, general wellness gadgets, most supplements, and anything that isn't tied to a medical purpose. Buying ineligible junk to "use up" the balance just converts forfeited money into wasted money, which is not an improvement. The move is to spend it on care you were genuinely going to need anyway, pulled forward into December, not on a drawer of stuff you'll never open.
The Three Things to Do Before New Year's
First, log into your FSA portal today and find two numbers: your remaining balance and your plan's deadline rule, whether it's a hard December 31, a $680 carryover, or a grace period into March. Everything else depends on those two facts. Second, book the appointments now, the dentist, the eye exam, the dermatologist, because December calendars fill fast and an appointment on January 2 does you no good against a December 31 balance. Third, stock the genuinely useful eligible items, contacts, prescription refills, the medical supplies you actually use, up to what's left.
The FSA saved you real money on taxes back in January. Don't let it claw that savings back in the last week of December because nobody told you the money had an expiration date. It does, it's coming, and unlike almost everything else in insurance, this one is entirely in your control.