Medicare's Annual Notice of Change Is the Letter You Skip
It arrives by September 30, it is fifteen pages, and it is the one piece of mail that tells you exactly how your plan gets worse in January. The premium, the drug tiers, the doctors still in network. Skip it and you find out at the pharmacy counter in February, which is the worst possible place to learn.
Fifteen Pages You Were Never Going to Read
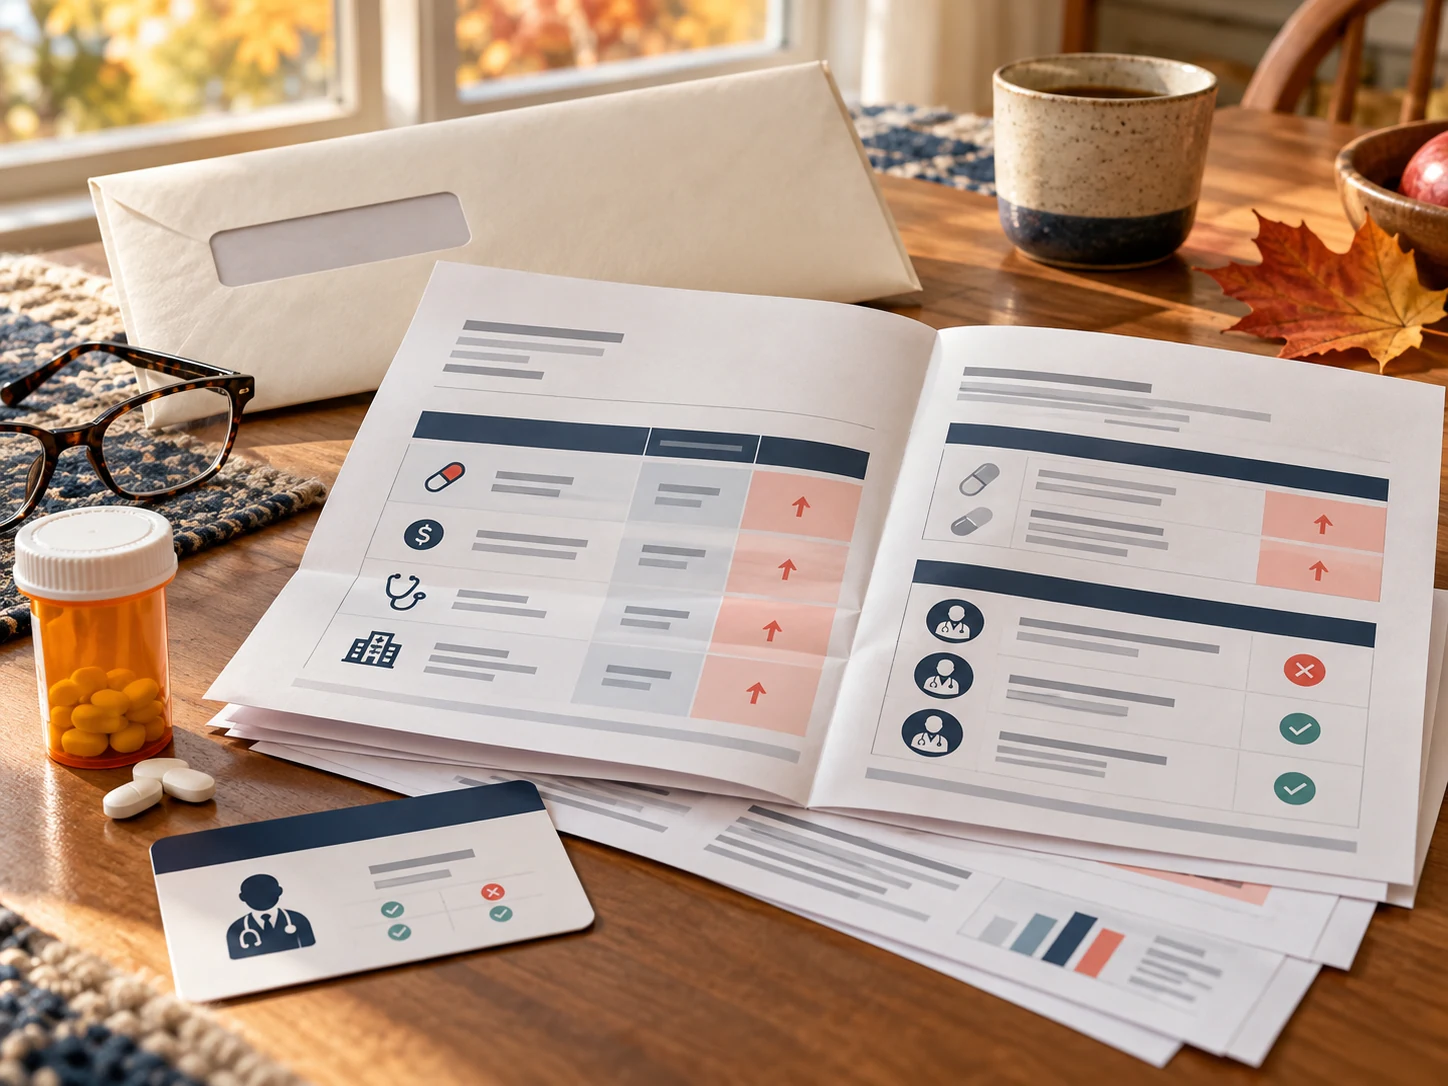
If you're on a Medicare Advantage or a Part D drug plan, a document called the Annual Notice of Change landed in your mailbox by September 30. It's thick, it's gray, and it's the single most useful piece of paper your plan will send you all year. It tells you, line by line, how your coverage changes on January 1. The premium. The deductible. The copays. Which drugs moved tiers. Which doctors are still in the network. You paid attention to none of it, because it looks like every other envelope, and I understand exactly why. It's designed to look ignorable.
Here's the cost of ignoring it. The changes it describes are not proposals. They already happened. Read the letter now and you can switch during open enrollment. Read it in February at the pharmacy, when your medication suddenly costs three times what it did in December, and you can do nothing until next year.
The Calendar Is Built to Give You Two Weeks
The timing isn't random. Plans have to send the notice by September 30. The Annual Enrollment Period, the window where you can actually change plans, opens October 15 and closes December 7. That gap, roughly two weeks, exists on purpose: it's your reading time. You get the bad news, you sit with it, and then the door to fix it opens.
Whatever you choose takes effect January 1. Miss December 7 and you're locked into your current plan's 2027 version, the one the notice just described, for the whole year. There's a separate Medicare Advantage window in the new year for limited changes, but it's narrower and it won't help most people. Treat December 7 as the real deadline, because for most decisions it is.
Read These Four Things, In This Order
You do not have to read all fifteen pages. You have to read four things.
The monthly premium, and whether it changed. That's the easy one. The drug deductible and the tier your specific medications sit on, because a drug sliding from a flat copay to coinsurance is where the painful surprises live. The out-of-pocket maximum for the year, your worst-case ceiling. And the provider network, specifically whether your own doctors and preferred pharmacy are still in it for 2027. A premium that rose a few dollars is noise. A specialist who dropped out of the network is the number that actually reorders your year, because out-of-network care under Medicare Advantage can cost you far more than the premium ever would.
The Tool That Does the Math for You
Medicare's Plan Finder at Medicare.gov is genuinely good, and almost nobody uses it. You enter your exact prescriptions, the real ones on your shelf, and it prices your total yearly cost across every plan available where you live: premium plus deductibles plus what each drug will actually cost you. It's the only way to compare plans on the number that matters, which is not the premium but the all-in annual cost for your particular list of drugs.
Run it every year, even if you love your plan, because the plan you love this year is not the plan you'll have in January. The formulary changed. The notice told you so. The Plan Finder turns that fifteen-page letter into one comparable number per plan, which is exactly what the letter should have done in the first place and didn't.
The Two Calls Before December 7
Call your pharmacy and ask them to confirm the 2027 tier and copay for each of your prescriptions under the plan you're leaning toward. They see this data constantly and they'll tell you in five minutes. Then call your primary doctor's office, the billing side, and confirm they'll still take your plan in the new year, because networks change quietly and a mailed notice won't always spell out a specific practice leaving.
That's the whole assignment. Open the gray envelope, read four things, run your drugs through Plan Finder, make two calls, and decide before December 7. It's an afternoon. The alternative is finding out at the counter, and the counter is the one place where knowing costs you nothing and not knowing costs you everything.